

SoLo Funds: Lend & Borrow
Solo Funds
- 4.2
- 5.01K Reviews
- 500.00K
- Downloads
- Free
- Price
Screenshots
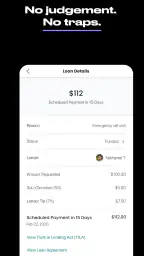
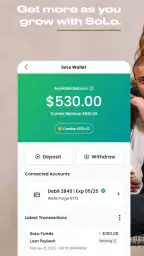
SoLo Funds: Lend & Borrow Pros and Cons
Pros
- User-friendly interface
- Quick application process
- No credit score impact
- Transparent fees
- Flexible repayment options
Cons
- Limited to small loan amounts
- Available only in the US
- High service fees
- Requires bank account linking
- Limited customer support
 Analysis by All-app
The first thing I’d keep in mind with a person-to-person money app is that a tidy interface cannot remove the decisions behind the transaction. A borrower still needs a repayment plan they can live with, and a lender still needs to be comfortable with the possibility that repayment may not happen as expected. That is where SoLo Funds: Lend & Borrow deserves a careful look: it brings both sides of a financial exchange into one place, but it does not make either side risk-free.
Where the process can feel less simple
SoLo Funds is a finance app from Solo Funds, built around connecting people seeking money with people willing to lend. That arrangement can feel more direct than going through a bank, yet it also asks users to think about trust, timing, and personal affordability. I would not treat a quick, phone-based process as a reason to borrow casually. Before making a request, I’d work out the amount that actually solves the immediate problem and the date by which repayment is realistic.
For lenders, the choice is not simply whether spare money is available. The more useful question is whether that money can remain unavailable for a while, or potentially be lost, without disrupting rent, bills, savings goals, or other commitments. A safety feature such as Payback Protection may sound reassuring, but I would read its terms and limits before relying on it. No protection label should replace checking what it covers or deciding whether the underlying risk suits you.
One practical snag in peer-to-peer borrowing is that a request and a completed loan are not the same thing. A person who needs funds for a bill due immediately should not assume that another user will accept the request in time. I’d keep a backup plan for urgent expenses, and I would avoid making a financial commitment based on money that has not arrived. This is a useful distinction between SoLo’s community-based model and a conventional credit product with a more familiar application route.
Checks I’d make before relying on it
The app is free to download, rated for Everyone, and has an average rating of 4.2 from around 21,000 ratings. It has passed 500,000 installs, and its current version is 2.9.11, with Android 8.0 as the minimum operating system. Those details offer a sense of its availability and audience, but they do not tell me whether a particular request will be funded or whether a specific loan is suitable. I’d use the app’s current in-app terms as the guide for any decision involving money.
Before starting, I’d check that the phone has a stable connection, that the app is up to date, and that I can access the information or account details needed to complete the steps shown on screen. If a screen stalls, I’d first close and reopen the app, then try again on a reliable connection. I would not repeatedly submit the same request while unsure whether the first attempt went through; checking the app’s transaction or request status first can help avoid confusion.
It also helps to separate the two roles in your mind. If you are borrowing, focus on the repayment amount, timing, and the consequences of missing the plan. If you are lending, focus on the amount you can afford to put at risk and the terms attached to the offer. That small pause before tapping through is more valuable than trying to resolve doubts after money is already involved.
More Reads From Our News Desk

Switching to the Xbox App: What Changes in Your Gaming Routine

Coloring & Learn Review: A Satisfying Canvas, Cluttered Menus

Microsoft 365 Copilot on Your Phone: Who Actually Needs It?

Mafia City: The Crime Saga That Outshines Its Rivals

Woodturning Transformed: How OS Updates Enhance Your Craft

How Tiles Hop EDM Rush Redefines Music Gaming
The Concept Behind SoLo Funds
So, what’s the deal with SoLo Funds? Imagine being able to lend or borrow money with just a few taps on your phone. That’s right, this app connects people who need money with those willing to lend – all without the hassle of a bank. It’s peer-to-peer lending at its finest, and it’s changing the game for personal finance.
Diving Into the Features
Let’s talk features, shall we? One of the coolest things about SoLo Funds is how it allows you to set your own terms. Borrowers can specify how much they need and when they can pay it back, while lenders get to choose who they want to support. It’s like a financial matchmaking service!
Another sweet feature is the Payback Protection. Think of it as a safety net for lenders, ensuring they get their money back, even if the borrower defaults. This adds a layer of trust and security that’s crucial when dealing with personal finances.
Using it for a real cash-flow gap
Imagine a household facing a timing problem rather than a long-term shortage: a utility payment is due before income arrives, and the shortfall is small enough to repay from the next paycheck. In that situation, I’d compare the requested amount with the exact bill, not with the maximum amount the app might allow. I’d also set a repayment date that leaves enough room for ordinary expenses after payday, rather than choosing the earliest possible date just to make the request look attractive.
That kind of narrow, planned use is where a peer-to-peer option may be worth considering. It is less suitable for recurring expenses that remain unaffordable month after month. Borrowing to bridge the same gap repeatedly can hide a budget problem and make the next payday tighter. If the need is ongoing, I’d look first at changing the bill schedule, speaking with the provider, or getting help from a qualified financial counselor rather than turning a short-term loan into a routine.
The lending side calls for a different workflow. I’d decide on a maximum amount before browsing requests, then stick to it even if a story feels compelling. I’d avoid concentrating money I may need soon in a single loan, and I would not lend based on an assumption that Payback Protection guarantees a particular outcome. The useful habit is to evaluate each offer against personal finances and the actual terms, not against optimism or pressure to help.
How it compares with familiar options
Compared with a bank loan or a credit card, SoLo’s central difference is that people choose whether to lend to other people, rather than dealing only with a financial institution. That can make the experience feel more personal and give users a role in setting terms. It also means the process may depend on a lender choosing to support a request, so I would not count on it as a guaranteed source of cash on a fixed timetable.
A credit card may be more convenient for a purchase that can be paid directly by card, while an overdraft or a bank product may fit someone who values an established provider and a familiar account relationship. Those alternatives still have their own costs and conditions, so I’d compare the actual terms rather than assume one is automatically cheaper or safer. SoLo is most interesting when the peer-to-peer structure itself suits the user and the amount and repayment plan are clear.
For lenders, ordinary savings are the more appropriate place for money that must remain dependable and accessible. SoLo is not a substitute for an emergency fund, and I would not treat lending as a predictable return. The decision to participate should come only after essential savings and near-term obligations are covered. That trade-off is easy to overlook when an app frames lending as a way to help someone while putting idle cash to use.
Recovering from a confusing step
If a request or repayment does not appear to have updated, I’d avoid guessing at the cause. I’d reopen the app, check the relevant status or transaction details, and make a note of what the screen shows before trying again. If the issue persists, contacting the app’s support through its available in-app or official channels is a safer next step than sharing account information with someone who contacts you unexpectedly. I would never send passwords or verification codes in response to an unsolicited message.
Notifications can help keep track of activity, but I would not use a notification alone as proof that a payment is complete. I’d confirm important changes in the app itself and keep personal records of the amount, date, and repayment plan. This is especially useful if you are juggling several bills: a simple reminder in your calendar can prevent an app notification from being lost among everyday alerts.
When the app may not be the problem
Some friction comes from the situation rather than the software. A request may not fit a lender’s preferences, a connection may interrupt a step, or a user may need to review terms more carefully before proceeding. In those cases, restarting the app will not resolve the underlying decision. I’d distinguish a technical issue—such as a screen that will not load—from a financial outcome, such as a request that has not been accepted, and respond accordingly.
I would also skip the app if I needed guaranteed funds by a strict deadline, could not explain how repayment would fit into my budget, or felt pressured to lend more than I could comfortably lose. Someone who wants a conventional lender relationship, predictable access to credit, or a product designed for longer-term borrowing may be better served by comparing regulated options from banks or credit unions. SoLo’s community model is a specific approach, not a universal replacement for those choices.
User Experience and Design
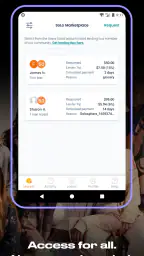
Now, onto the user experience. Navigating through the app is a breeze. It’s clean, straightforward, and just plain intuitive. You don’t need to be a tech whiz to find your way around. The design is sleek and modern, making the whole lending and borrowing process feel like a walk in the park.
The app also sends timely notifications, keeping you in the loop about your transactions. Whether you’re waiting for a loan to be approved or tracking a repayment, SoLo Funds keeps everything transparent and easy to manage.
Who I think will get the most from it
I can see the appeal for someone who has a temporary, clearly defined cash-flow gap, understands the repayment plan, and is comfortable using a person-to-person service instead of relying only on a bank. It may also interest a lender who wants to make individual lending decisions and has money set aside that is not needed for essentials. In both cases, the key is to use the app deliberately rather than letting convenience make the decision.
I would steer away from borrowing if the repayment depends on uncertain income, if another loan is already difficult to manage, or if the expense is likely to return each month. I’d also steer away from lending if a delayed or missed repayment would affect my own bills. These are not criticisms unique to SoLo; they are the practical boundaries I’d apply to any arrangement where one person’s money depends on another person’s repayment.
My Final Thoughts
All in all, SoLo Funds: Lend & Borrow is a fantastic app that brings a fresh perspective to personal finance. It empowers users by giving them control and flexibility, which is a huge plus in today’s fast-paced world. The app’s commitment to community-driven finance is both inspiring and practical.
So, if you’re in need of a quick loan or looking to put your extra cash to good use by helping others, give SoLo Funds a try. It might just be the financial sidekick you’ve been waiting for!
Frequently Asked Questions
What is SoLo Funds and how does it work?
SoLo Funds is a peer-to-peer lending platform that connects borrowers with individual lenders. Users can request short-term loans up to $1,000, setting their own terms and timelines, while lenders can choose to fund these requests based on their preferences. The app facilitates these transactions securely and efficiently, making it a convenient solution for those in need of quick financial assistance or looking to earn extra income by lending.
Is SoLo Funds safe to use?
Yes, SoLo Funds prioritizes the safety and security of its users by implementing robust security measures. The app uses encryption to protect personal and financial information. Additionally, SoLo Funds has a comprehensive verification process for all users to prevent fraud. The platform also offers a community-based rating system to maintain trust between borrowers and lenders.
What are the fees associated with using SoLo Funds?
SoLo Funds does not charge interest on loans; instead, borrowers can choose to offer a voluntary tip to lenders as a gesture of gratitude. Additionally, there is a small platform fee for each transaction, which helps maintain the service's operations. This fee structure makes SoLo Funds an affordable option for both borrowing and lending money compared to traditional services.
How quickly can I get a loan through SoLo Funds?
The speed at which you can receive a loan on SoLo Funds depends on several factors, including the amount requested and the number of lenders available. Generally, loans are funded within a few hours to a couple of days. The app's design facilitates quick transactions, allowing borrowers to receive funds promptly, especially during financial emergencies.
What happens if I can't repay my loan on time?
If you find yourself unable to repay your loan on time, SoLo Funds encourages open communication with your lender to negotiate an extension or alternative repayment plan. The platform emphasizes community support and understanding, but consistently failing to repay loans can affect your credibility and future borrowing opportunities on the app. It's crucial to manage your loans responsibly.


